Prime Minister Mark Carney opened the second and final day of the Canada Investment Summit in Toronto by announcing a tax “mega deduction” for business investment, opening Canada’s four largest airports to private capital, and making new commitments in Canadian defence, critical minerals, and large-scale infrastructure and technology funds.
The Prime Minister’s Office (PMO) says the Sept. 14–15 summit, attended by investors from nearly 30 countries, generated nearly $500 billion in new investment commitments in Canada.
The total includes financing from major Canadian banks, pension funds, and institutional investors, along with Bell Canada’s planned $52.5 billion expansion of its AI infrastructure in Saskatchewan.
“We unleashed nearly $500 billion of new investment into Canadian businesses and infrastructure—and this is just the beginning,” Carney said. “The world sees our strengths and ambitions, and we will harness this moment to generate lasting growth, opportunity, and prosperity for Canadians.”
Carney next heads to Strasbourg, France, and Liverpool, UK, for visits aimed at deepening ties with European nations this week.
The prime minister is scheduled to attend the State of the Union Address by European Commission President Ursula von der Leyen on Sept. 16 and will subsequently deliver remarks before the European Parliament on Sept. 17.
Former Prime Minister Stephen Harper, who now serves as board chair of the Alberta Investment Management Corporation, delivered the keynote speech at the end of the summit, highlighting Canada’s “economic diversity.”
“We must be committed to retaining this incredible economic diversity, and we cannot allow the Trump administration to hollow out our industrial capacities,” he told the audience.
“I do congratulate our current federal government on the measures it has taken to fast-track major project approvals, especially for projects in the oil sands. These changes are welcome, and they are very important. However, more does need to be done,” he added.
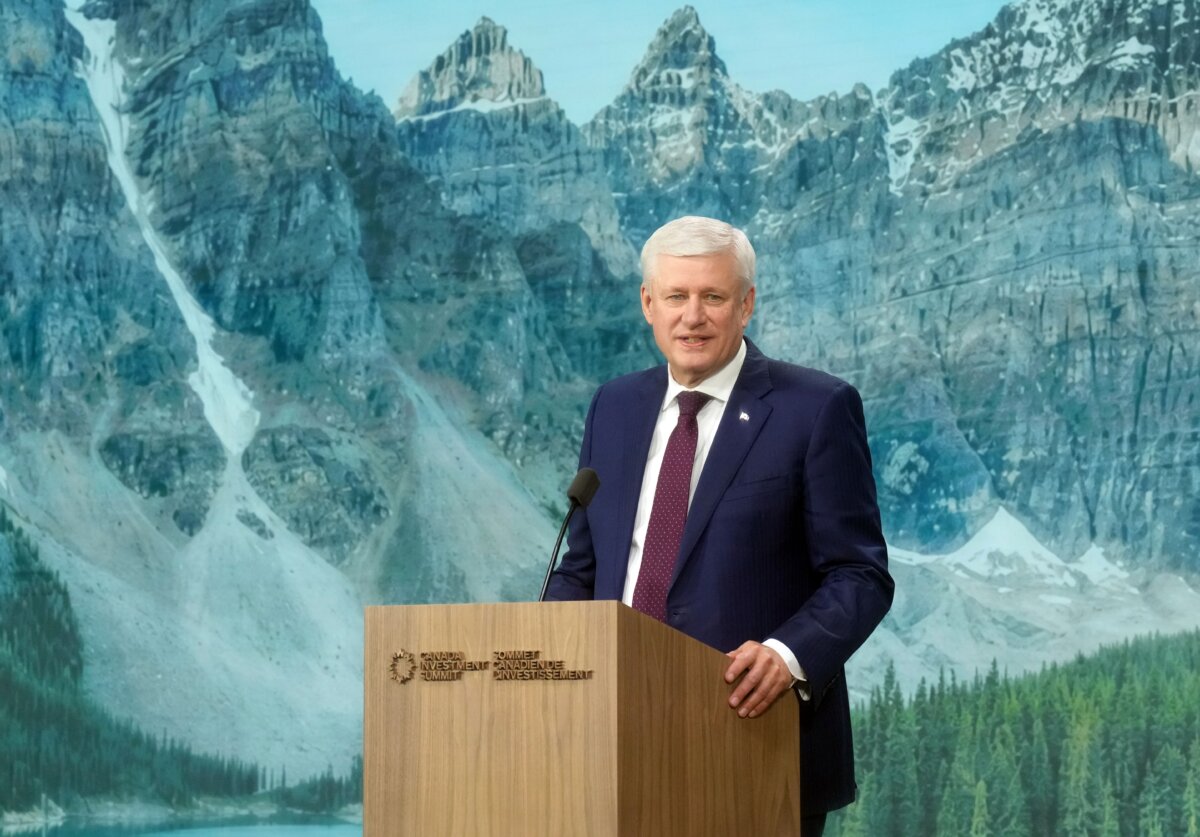
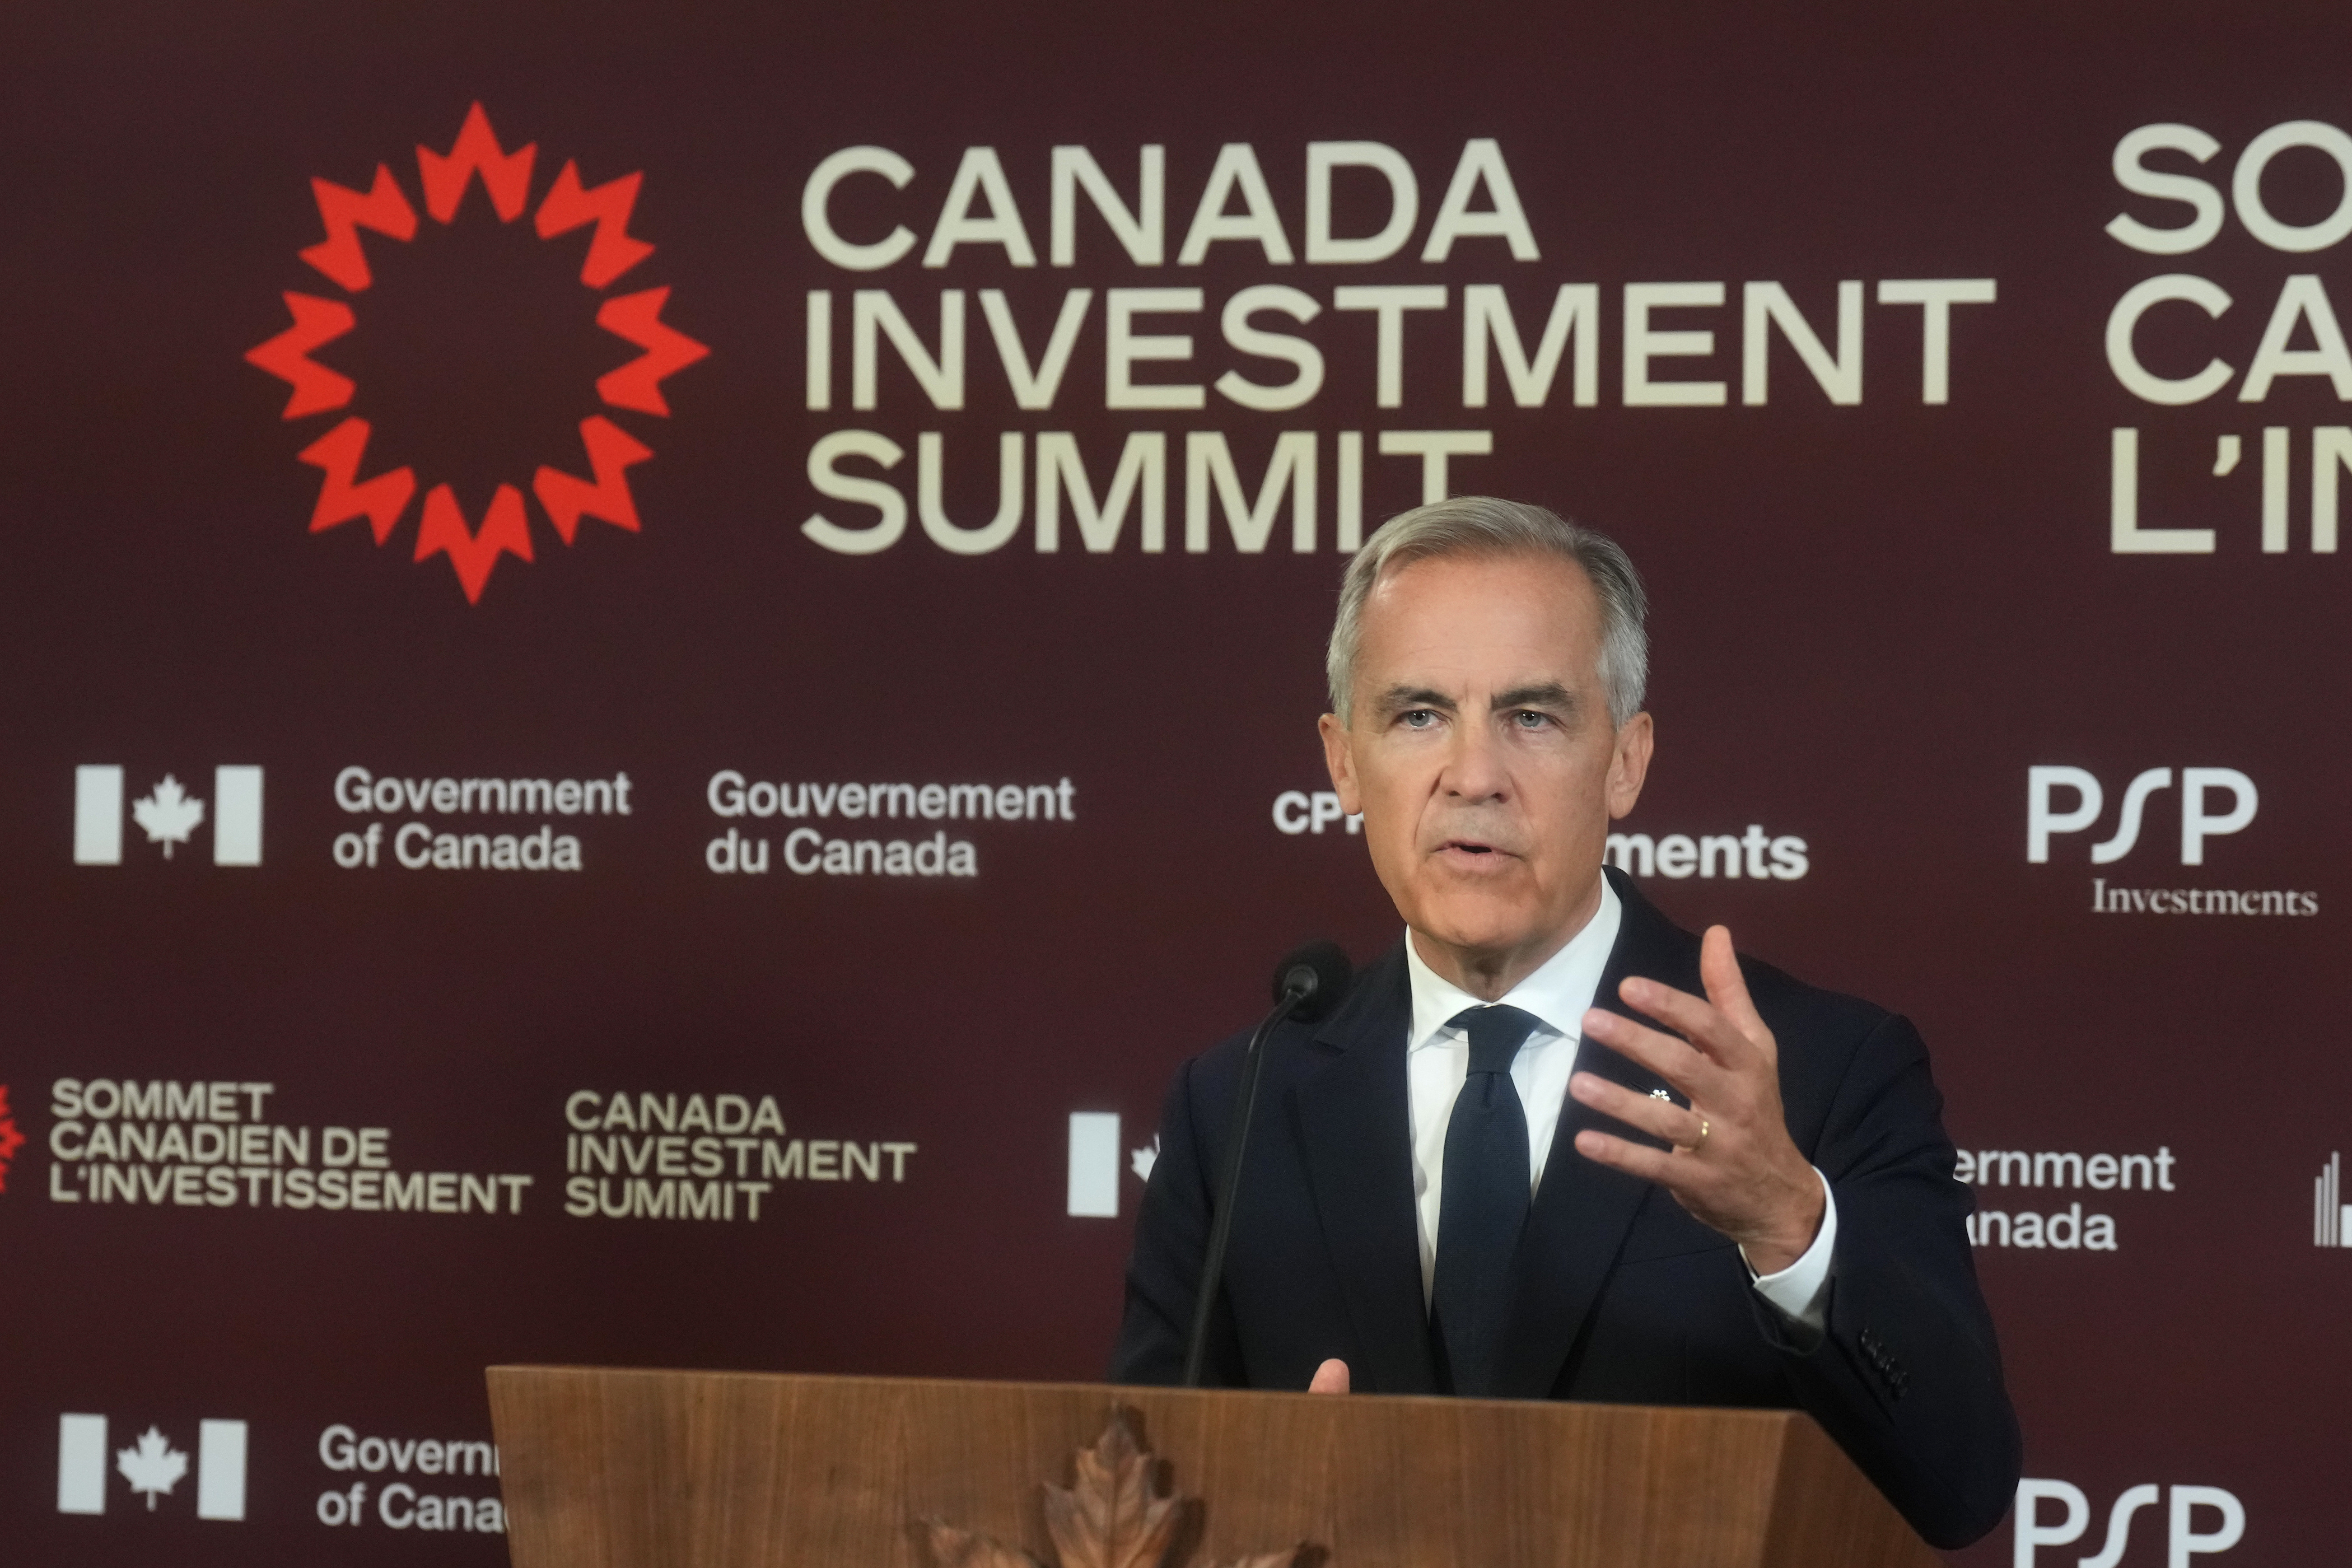 Prime Minister Mark Carney speaks during a news conference at the 2026 Canada Investment Summit in Toronto on Sept. 15, 2026. (The Canadian Press/Nathan Denette)
Tax Break
On Sept. 15, Carney announced the proposed Productivity Mega Deduction, which would let businesses write off the full cost of a broadened set of new investments in the year they become available for use, rather than deducting the cost gradually over several years.
Ottawa noted that examples of qualifying investments include business spending on machinery, mining property, pipelines, railway track, roads and bridges, software, and computer equipment.
The Department of Finance says the new tax break will cost the federal government roughly $36 billion over five years starting in 2026–27. It adds that the measure will reduce the marginal effective tax rate—the tax imposed on an additional dollar of business investment—on new business investment from approximately 13 percent down to 6.4 percent.
Private Stakes in Airports
Also on Sept. 15, Carney announced that Ottawa will open Canada’s four largest airports, in Montreal, Calgary, Vancouver, and Toronto, to private investment via long-term concession agreements.
While Ottawa would retain control of the land and assets, private operators would be permitted to take a larger role in operating and managing the airports, including expansion plans.
The move could raise “tens of billions of dollars,” according to Carney, who said the proceeds would be used for regional airports, local transportation projects, and a proposed national broadband network with more direct and secure links to Europe and Asia.
Conservative MP Michelle Rempel Garner said the announcement raises a number of questions, including what impact there may be on airport fees for travellers and whether foreign investors would now be allowed to own “critical Canadian infrastructure.”
NDP Leader Avi Lewis criticized the announcement, arguing that “privatizing our airports benefits no one but corporations out to make a profit.”
$50 Billion Maple Fund
In addition, on Sept. 15, the Canada Pension Plan Investment Board (CPP Investments) and Brookfield Asset Management announced the launch of the Maple Fund, a joint framework that they said could include up to $50 billion invested in Canadian infrastructure and key industries over the initial five years, with the two organizations each committing to provide up to $25 billion in equity capital.
The PMO included the Maple Fund as part of investment commitments totalling nearly $100 billion that it received from pension funds, insurers, and other institutional investors at the summit.
Additional commitments came from Radical Ventures, a venture capital firm that says it had raised more than US$1 billion in funds and backed a number of large Canadian financial organizations, including CPP Investments and BMO. The funds’ goal is to provide financing to AI companies as they expand.
The PMO said Radical ultimately plans to invest and mobilize CA$4 billion through the initiative.
On Sept. 15, the Business Development Bank of Canada also specified how it will allocate $1 billion in funding toward defence usage.
It said $500 million from its Defence Platform will go toward Canadian and allied funds focused on defence and dual military-civilian usage technologies, while an additional $200 million will boost its StrongNorth Fund to $500 million. The venture capital fund invests in young Canadian companies developing technologies for military and civilian use.
Build Canada Strong Act
Carney added that a new piece of legislation titled the Build Canada Strong Act will be tabled by his government, building on the Building Canada Act, which was enacted in June 2025 as part of the One Canadian Economy Act.
The government says the proposed legislation would accelerate project approvals beyond those being considered by the PMO.
“We have already begun accelerating major nation-building projects through the Major Projects Office. Now we will apply that same urgency and efficiency more broadly through the new Build Canada Strong Act,” Carney said.
“For projects and supply chains, our standard will be simple: One project. One review. One year.”
The Major Projects Office (MPO) was launched in August 2025 with the stated goal of reducing approval timelines for projects deemed in the national interest to no more than two years.
Carney on Sept. 15 did not specify how the new one-year standard would interact with the MPO’s existing two-year approval timeline.
Conservative Leader Pierre Poilievre said on Sept. 15 that he is happy Carney has been hosting the investment summit this week and attempting to attract more investment to the country, but that the government should go beyond “speeches, summits, and symbolic signing ceremonies” and deliver results to tackle affordability issues in Canada. He added that to boost the economy, the government should cut more taxes, such as the industrial carbon tax, and take more measures to remove red tape.
Day 1 Announcements
The second day of announcements from the summit follow a number of new investments and measures unveiled on the first day of the summit.
These included an agreement between Bell and the Saskatchewan government for expansion of the telecommunication company’s AI plans in the province, a deal that could exceed $52.5 billion, according to the PMO.
Just prior to the summit, BMO also announced plans to mobilize up to $70 billion in various sectors of Canada’s economy including energy and electricity infrastructure, mining and critical minerals, transportation, AI, oil and gas, defence, and computing.
This was followed by a Sept. 14 commitment of $150 billion over five years toward key Canadian economic sectors by TD Bank and more than $100 billion committed by Scotiabank to help grow Canadian and North American economic competitiveness.
On Sept. 14, Finance Minister François-Philippe Champagne also detailed $140 million being invested by the Canada Growth Fund in a copper and palladium mining project in northwestern Ontario. In addition, he touted the Canada Revenue Agency’s Advance Income Tax Rulings program.
The program, which gives investors binding guidance on how tax laws would be applied to planned transactions before they commit funding, aims to deliver an assessment within 90 business days of receipt of the required information on a planned transaction.
In addition, Manitoba Premier Wab Kinew said his government will waive provincial sales tax on major spending tied to development at the Port of Churchill, with the exemption applying to proposals involving a new energy corridor and liquefied natural gas facilities, railroad upgrades, and improvement of icebreaking capacity to support year-round shipping from the port.