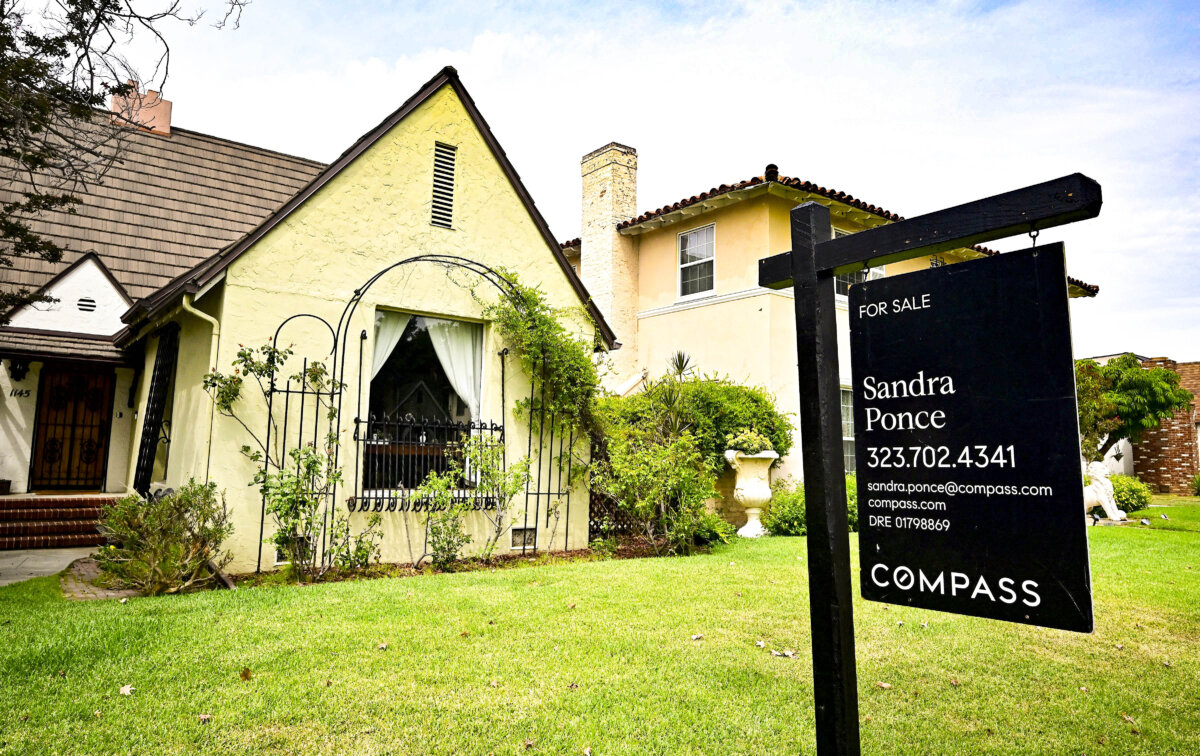
Monthly mortgage payments in the United States have fallen to a six-week low as home prices decline, according to real estate brokerage Redfin.
The median monthly mortgage payment hit $2,755, down from $2,820 a month ago, Redfin said in a Nov. 12 report.
The average weekly rate on a 30-year fixed-rate mortgage was 7.11 percent for the week ending Nov. 12, down from 7.4 percent in early October, according to data from Freddie Mac.
Rates crossed the 7 percent level in late September and have remained above it, but have declined over the past four weeks.
The median home sale price was $388,613 for the four weeks ending Nov. 8, down 0.9 percent year-over-year, Redfin said.
Median home-sale price fell 0.4 percent year-over-year in October, the first annual decline in three years.
“It’s a buyer’s market, but not many people can afford to buy,” Chen Zhao, Redfin’s head of economics, said in the Nov. 10 report. “That could start to shift a bit, now that sale prices are closer to reflecting the shape of the market.”
“House hunters in most of the country should know that the price they see on a listing may very well be a starting point; they should try offering below the asking price, and negotiating for closing costs, repairs and maybe even mortgage-rate buydowns.”
The housing market remains subdued despite easing home sales prices and lower mortgage rates.
Pending home sales, a leading indicator of existing home sales, remained at their lowest level since 2021, Redfin said in its latest statement. These are home sales contracts that have been signed but not yet closed.
The brokerage said pending home sales could have fallen sharply if mortgage rates hadn’t dipped in recent weeks.
Existing home sales fell 8.8 percent year over year in October, the National Association of Realtors (NAR) said in a Nov. 12 statement.
“Home buying is difficult when mortgage rates have climbed to their highest levels since 2000, aside from a single month in 2023. As a result, home sales fell to their lowest level since August 2010,” NAR chief economist Lawrence Yun said in the statement.
“Based on the current underwhelming home sales pace at a time of consistent job growth, there could be sizable pent-up demand if mortgage rates decline,” Yun said.
Affordability Challenge
Builder confidence in the market for newly built single-family homes fell in October from the previous month to its lowest level since June 2012, the National Association of Home Builders (NAHB) said in an Oct. 19 statement.
High energy and material costs have lowered builder sentiment, the association said. NAHB chief economist Robert Dietz cited “significant affordability challenges” as a factor squeezing the housing market.
President Donald Trump signed an executive order on Oct. 22 to lower housing costs. The order asked secretaries of the U.S. Department of Agriculture and the Department of Veterans Affairs to lower interest rates on single-family home loans. It also sought to ease mortgage insurance costs for certain homeowners.
The Department of the Treasury proposed regulations last month seeking to restrict large institutional investors from buying single-family homes. The move codifies a key requirement of Trump’s Jan. 20 executive order—Stopping Wall Street From Competing With Main Street Homebuyers.
The Treasury proposed that large institutional investors generally may not buy a single-family home beginning Jan. 7, unless the transaction is exempted under the 21st Century ROAD to Housing Act, such as for build-to-rent programs.
“Treasury is working to ensure American families and workers have a fair shot at purchasing homes in their communities by increasing housing supply and limiting large institutional investors’ role in the market, while supporting a strong, stable housing market and avoiding unnecessary disruption,” Treasury Secretary Scott Bessent said in the Oct. 22 Treasury statement.