Commentary
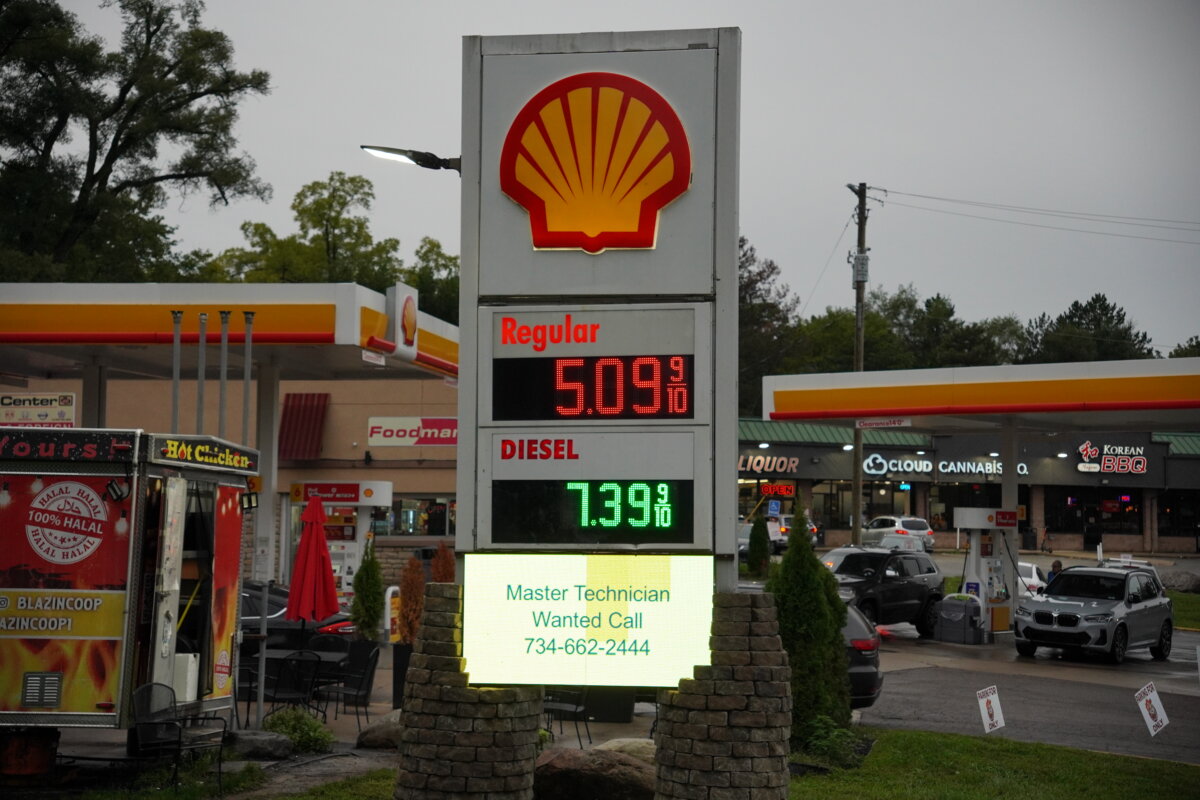
Yes, we are experiencing high gas prices, but the factors contributing to them are being addressed, and gas prices will come down in a matter of months. However, looking beyond the short-term reveals that real substantive reforms have structurally improved our economy and are poised to supercharge it.
Don’t give credence to so-called experts declaring the 1.5 percent second-quarter gross domestic product (GDP) growth to be proof positive that President Donald Trump’s economic revival has failed. Such a conclusion is based on ignorance and a fast-food mentality that discounts the fact that creating the foundation for a super-industrial cycle takes more than a few months. It takes at least a couple of years. And as we approach the end of the second year of the Trump administration, things are aligned to create a massive boost in GDP, with the added benefit that much of it will come from the United States clawing back some of the manufacturing it lost after the Clinton administration led the charge to give China most-favored-nation status.
Along with real wage growth that is starting to make up for the loss of real wages experienced during the inflation-heavy Biden administration years, we are talking about massively increasing the hard GDP that comes from increasing U.S. industrial mass and productivity, versus the soft GDP that comes out of debt-fueled consumerism and the service sector.
Last quarter, mass quantities of high-value telecommunications gear, advanced semiconductors, and heavy industrial machinery crossed our borders. While these massive incoming shipments technically created a temporary drag on quarterly GDP math, these capital goods are destined for our factory floors, where they will contribute exponentially to future, hard GDP by expanding domestic manufacturing mass. Because industrial production has a massive economic multiplier dwarfing that of the service sector, it acts as a wealth generator rather than a wealth consumer. Hence, lumping a million-dollar lithography machine destined to print advanced microchips in with a container of cheap televisions from China is either an act of economic ignorance or a purposeful attempt to deceive.
Build First, Produce Later
As of late 2026, the total announced and committed private-sector investment in U.S. manufacturing and industrial projects since January 2024 stands at approximately $2.084 trillion. Billions of dollars invested in these commitments have already resulted in ground being broken for new facilities, with many hundreds of billions of dollars set to go toward construction projects due to break ground over the next two years. Machine-tool orders are running far above what they were a year ago. So while construction continues, the machines and systems that form the heart of factories are being installed and readied for production, a definitive leading indicator of near-term production and GDP acceleration. This is the kind of activity America needs to reverse its industrial decline while simultaneously reducing its dependence on an entity that does not have the best interests of the United States at heart.
Beyond using presidential authority to pave the way for industrial revival, the “One Big Beautiful Bill Act” put into law full and accelerated expensing of capital investment. Literally thousands of other reforms are making it easier to do business in the United States. And while settling on a balanced tariff policy is still a work in progress, acknowledging that some tariffs are necessary and beneficial for ensuring that working-class people can count on real-wage gains is a refreshing and much-needed change. Further, while it is utterly unrealistic to expect these new economy-friendly policies to remove the pain of the huge price increases in daily necessities experienced over the 2021 to late 2024 period, it is encouraging to know that real wages are increasing as new private-sector jobs are being added, even as federal government positions are reduced.
The Next Two Years Will See Significant Boosts in Hard GDP
Over the next two years, much of the modernization and new factory construction will begin to bear fruit. Factories already built will begin producing. A large slice of last quarter’s capital-goods imports is computers, chips, and telecom gear for data centers—not consumer goods. As noted, while these imports initially decrease GDP, the belief is that the compute they produce will result in increased productivity that, over a relatively short period of time, will increase GDP far more than the GDP lost due to imports. And the GDP they will produce will be substantial, real GDP versus the GDP that comes from debt-fueled consumer spending.
Beyond 2028
Near-term growth matters, but the long-term foundation being built will accelerate American reindustrialization and break China’s control over defense-critical resources such as steel and rare earth minerals. For decades, the United States ceded steel production to foreign competitors, exporting millions of tons of scrap metal to China, only to buy back high-profit, value-added products—a dynamic mirroring of a colonial system with China being the colonial power. This embarrassing pattern is being dismantled as the United States builds advanced domestic steel-making capacity capable of recycling its own scrap. Key projects include the new Mesabi Metallics mill in Iowa, which will ingest millions of tons of scrap starting in 2030 to reach an annual 10-million-ton output, and a newly opened Minnesota iron mine—the first new domestic iron mine in 50 years—providing direct-reduction grade ore to support this production.
Rare Earth Mining, Refining, and Magnet Production
Because rare earth minerals and magnets are defense-critical, the United States is moving aggressively to dismantle China’s near-monopoly on their extraction and manufacturing. Under the Trump administration, critical initiatives have been fast-tracked. These include the launch of “Project Vault,” a $12 billion program to establish a U.S. Strategic Critical Minerals Reserve, alongside multibillion-dollar Pentagon and Export-Import Bank partnerships. These federal interventions guarantee price floors for domestic miners such as MP Materials, expedite processing facilities for USA Rare Earth, and fund localized magnet-manufacturing plants such as Vulcan Elements to secure the entire domestic supply chain. These initiatives will add to real substantive GDP and create thousands of new high-paying jobs.
High Gas Prices Hurt But…
Yes, gas prices are high, but the world’s oil producers and shippers, led by the United States, are moving quickly to ameliorate Iran’s ability to affect oil and gas availability. Meanwhile, a true economic renaissance is underway in the United States that is already increasing real wages and, with the temporary exception of gas prices, has gotten inflation under control. U.S. national security concerns, including the dire threat of the No. 1 sponsor of terror getting the nuclear bomb, are being addressed, and we are revitalizing an industrial base hollowed out by decades of China’s predatory, anti-free trade practices and a U.S. Congress asleep at the wheel. Don’t let a few months of pain at the pump obscure these facts.
Views expressed in this article are the opinions of the author and do not necessarily reflect the views of The Epoch Times.