News Analysis
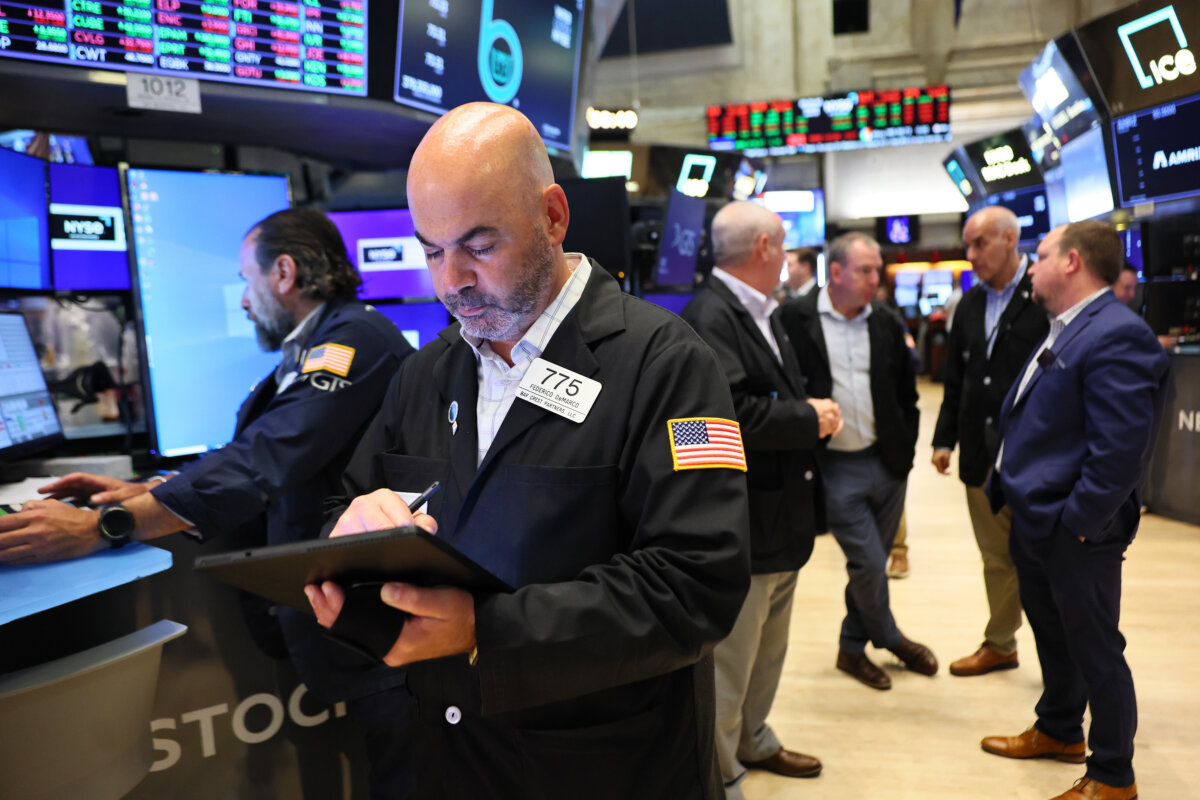
After a brief pause over the previous two weeks, U.S. stocks staged a broad and sustained rally this week, closing sharply higher amid signs of easing tensions in the Middle East and in global trade. Meanwhile, falling oil prices and bond yields further fueled the gains.
The S&P 500 Index closed at 6,173 on June 27, up by 3.44 percent for the week. The Dow Jones Industrial Average rose by 3.82 percent to finish at 43,819. The Nasdaq Composite Index surged by 4.25 percent to 20,273, while the Russell 2000 added 3 percent.
Wall Street began the trading week on June 23 amid rising uncertainty over the escalating conflict in the Middle East. Much of the concern was centered on the oil market, where traders and investors tried to gauge the impact of the Iran–Israel conflict on prices.
Initially, the price of black gold hovered near the $75 mark, but it quickly headed south—dropping 7 percent on the day—as it became clear that the escalation of the conflict between the two sides wouldn’t disrupt oil supplies from Iran.
Oil prices continued to sell off on June 24 as the United States brokered a cease-fire between Iran and Israel, giving equities a significant boost.
The rally was broad and led by big tech companies, with Nvidia heading toward new highs as the “risk-on” trade returned to Wall Street.
Meanwhile, easing bond yields added to positive sentiment, with the benchmark 10-year Treasury yield sliding below the 4.30 percent mark.
Bond yields came under pressure from lower oil prices, which bodes well for headline inflation, the critical driver of long-term interest rates.
Long-term interest rates, in turn, serve as the discount rate in almost every equity valuation model.
As a result, lower interest rates increase the present value of future earnings, making equities more attractive compared with alternative investments.
Another factor contributing to lower bond yields was a weak Consumer Confidence report from the Conference Board, with both the Present Situation and Expectations indexes declining from April to May.
“Consumer confidence weakened in June, erasing almost half of May’s sharp gains,” Stephanie Guichard, senior economist of global indicators at The Conference Board, said following the release of the report.
Guichard said the decline in consumer confidence was broad-based, with both assessments of the present situation and expectations for the future decreasing.
Weak consumer confidence revived hopes among traders and investors that the Federal Reserve could cut interest rates sooner rather than later.
This sentiment was reinforced on June 26 by a Labor Department report showing that continuing jobless claims in the United States rose to 1,974,000 in the week ended June 14. This is the highest level since November 2021 and exceeds market expectations of 1,950,000.
However, a couple of additional economic reports released on June 27 painted a somewhat different picture of the state of the U.S. economy.
The University of Michigan’s consumer sentiment index for the United States was revised higher to 60.7 in June, up from a preliminary reading of 60.5 and 52.2 in May.
The increase was driven by broad-based improvements across multiple facets of the economy, with expectations for personal finances and business conditions rising by about 20 percent or more.
Meanwhile, the Federal Reserve’s closely-watched core personal consumption expenditures (PCE) price index, which excludes volatile food and energy prices, rose by 2.7 percent in May compared with a year earlier, surpassing market expectations of 2.6 percent and the central bank’s target of 2 percent.
“Today’s [June 27] PCE reading showed that inflation is still not spiraling out of control. However, it did snap a three-month streak of lower year-over-year readings, while last month’s figures were revised higher,” Bret Kenwell, a U.S. investment analyst at eToro, told The Epoch Times.
He said the PCE report wasn’t a significant scare for the markets, but it may dampen the faint hopes investors had for a July rate cut and could lead to some hesitation as stocks approach record-high territory.
However, stocks rallied to new highs throughout the June 27 session, lifted by news from Washington of a tariff truce with Beijing.
Robert Ruggirello, chief investment officer at Brave Eagle Wealth Management, sees volatility ahead with the likelihood of double-digit gains.
“While stocks are back at record highs, that does not mean that there won’t be volatility during the second half of 2025,” he told The Epoch Times.
“We are expecting more volatility and wouldn’t be surprised if it were in both directions. Single-digit annual stock market returns, both positive and negative, are rare, and we wouldn’t be surprised to see a double-digit annual return in either direction.”