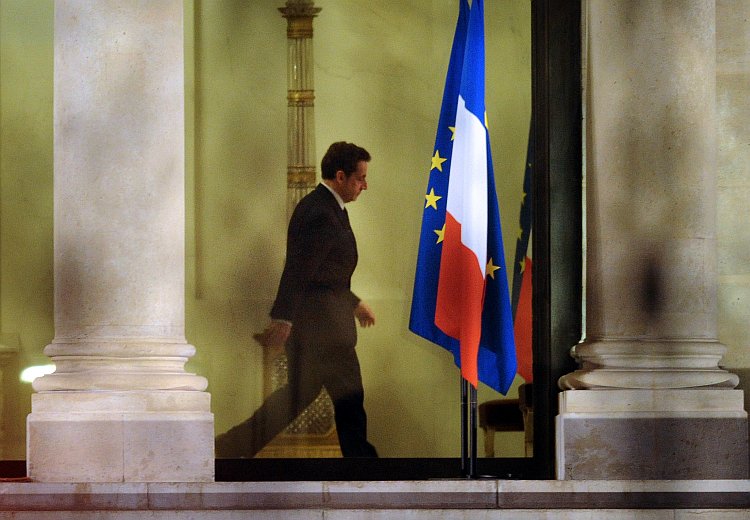

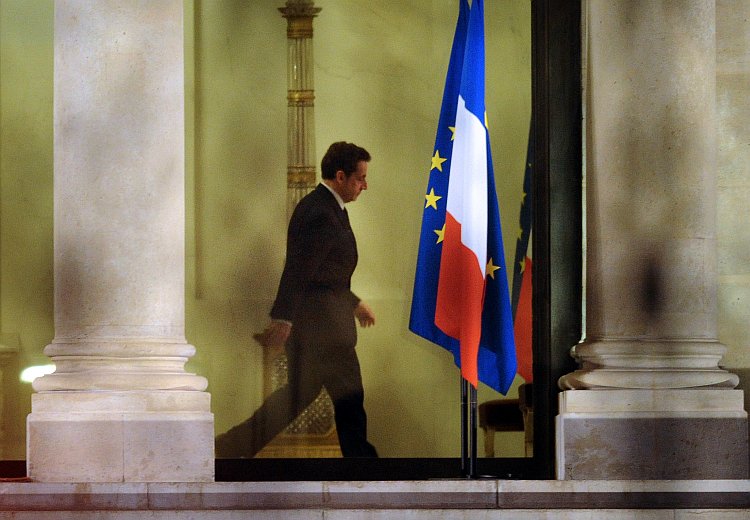
PARIS—Friday 13 was indeed a bad luck day for France with the announcement of the Standard & Poor’s downgrading French sovereign debt from AAA to AA+ along with eight other European countries.
The suspense had been mounting since last summer with the ever-increasing gap in interest rates between France and Germany reinforcing predictions that S&P’s downgrading of France was inevitable.
The 16 summits “of last chance” held between French President Nicolas Sarkozy and German counterpart Angela Merkel helped maintain the illusion for Paris that it could weather the storm. But S&P’s threat on Dec. 5 to lower the ratings of 15 European countries, including the six triple A countries, forced the French government to finally accept the omen.
Friday’s announcement by Fitch Ratings—a subsidiary company of the French Financial Group Fimalac, headed by Marc Ladreit de Lacharrière, a friend of Sarkozy’s—that “the French rating would not be lowered in 2012” wasn’t sufficiently convincing for S&P, any more than France’s second round of budget cuts passed by Parliament at the end of 2011.
In its accompanying remarks, S&P gave several reasons for the downgrade. First was the lack of any significant advances after the last European summit on Dec. 9, in particular “on the subject of supplementary resources and the necessary flexibility to support the countries of the eurozone faced with market pressure.”
At the same time, said S&P, if the European agreement recognizes the necessity to reduce budget deficits, no mention was made of “the increasing outside instabilities or of the diverging competition between European countries.” For the agency, austerity budgets alone without measures to support employment or maintain consumption, will lead to lower tax revenues and a self-destructive cycle.
Especially for France, S&P highlighted its good health and diversified economy, but questioned “the high levels of the sovereign debt, as well as labor market rigidities.”
The agency thus advises the government to pursue its “strategy of budgetary reinforcements and its structural reforms,” but indicate that there is still a
“one-in-three chance” that the ratings will again be lowered if the results are not as expected. This would be particularly likely if growth is below the current government forecast of 1 percent in 2012 and 2 percent in 2013, or if France should need to reinforce its financial engagements in the eurozone.
Looking to minimize the political fallout by comparing France to a student who, used to getting 20/20, receives 19/20 which it knew was coming, the finance minister stated that government management is not at issue. Rather, the downgrade was because of the overall crisis in the eurozone, and that it won’t give rise to any new austerity measures.
In his address on Saturday, Prime Minister François Fillon confirmed his pledge to take new steps to enhance France’s competitiveness and growth. He said that the upcoming Jan. 18 summit with the country’s social partners, will address themes of unemployment, business competitiveness, and social welfare financing to reduce labor costs. He also announced a future debate with the local communities on efforts to reduce deficits.
Opposition candidates in the upcoming presidential elections criticized the government for a perceived smugness.
Socialist Party candidate François Holland pointed out that the loss of the triple A rating is “the first time, ever since the states have been graded, that France has fallen behind Germany.” France’s budget deficit, he pointed out, was 5.5 percent of GDP compared to 1 percent in Germany.
Centrist candidate Francois Bayrou for the Democratic Movement, rejected the back-to-back succession of Conservative and Labor governments, saying “each carries a share of responsibility.”
National Front Party candidate, Marine Le Pen, criticized Sarkozy’s failures in forecasting the breakdown of the eurozone.