Commentary
Every three years, the committees that write America’s model building codes sit down and rewrite them. Every three years, the codes get longer. I have yet to find the cycle in which they took out more than they put in.
Regulation works like a ratchet. Each click tightens. Nothing ever gets loosened up. Every individual requirement sounds reasonable on its own, e.g., thicker insulation, another specialty breaker, ductwork pressure-tested by a contractor, a mechanical fresh-air system for houses the previous code made airtight. No one wants to vote against safety, and no one shows up at the hearing on behalf of the young couple who will be priced out of the house.
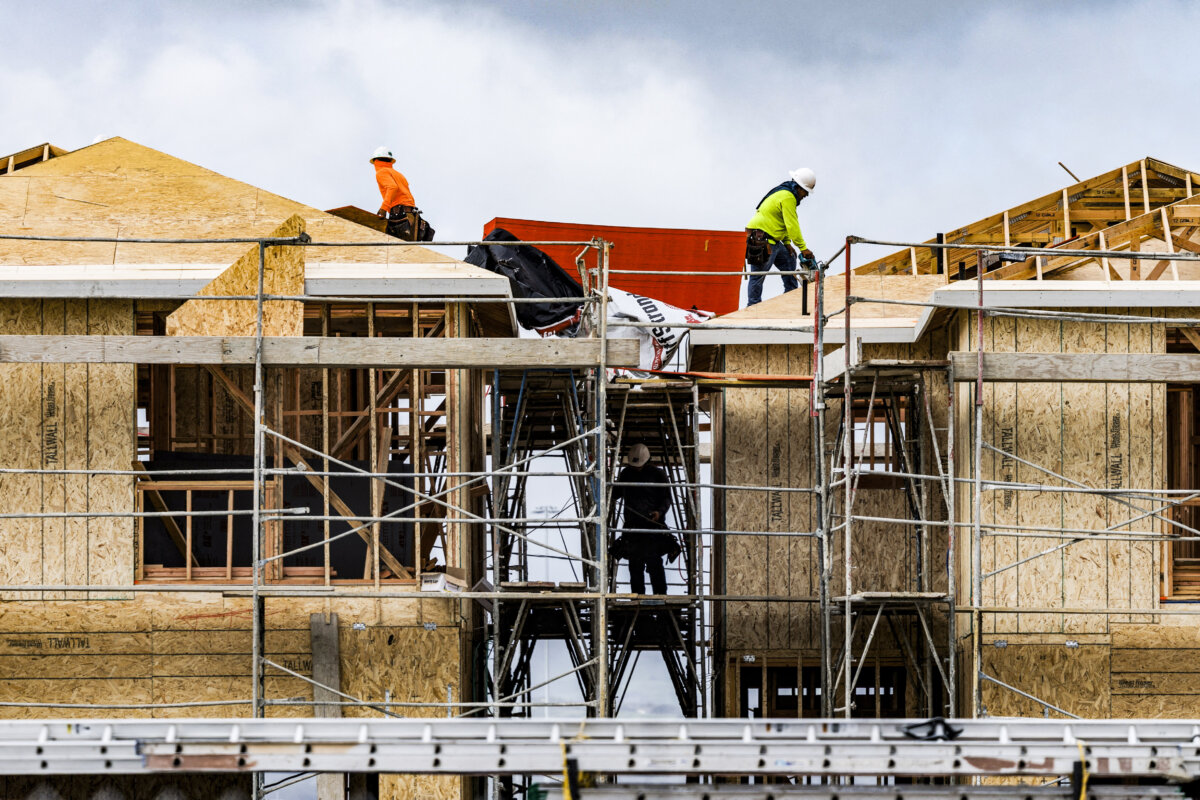
The National Association of Home Builders, in June, calculated that government regulation now adds $131,734 to the price of the average new home, more than a quarter of what the buyer pays. Code changes made over just the past decade account for $40,288 of that. Five years ago, the figure was $24,144. Many of the very companies whose products you are forced to buy to comply with the code have seats at the table drafting the regulations you must adhere to.
Some energy provisions do pay for themselves in lower power bills. A study funded by the code writers and the insurance industry naturally found that home prices did not rise after most code adoptions. Still, a family buying a home needs the down payment today, not utility savings in a decade. The electrical code makes the problem easy to see. North Carolina’s own fiscal analysis found that a standard two-pole breaker for an electric range costs about $17, while the ground-fault version the 2023 code now requires costs about $112. Nebraska, Iowa, and Indiana adopted the new electrical code without some of those expanded requirements. That should be routine rather than remarkable for states to do, but it is uncommon.
Making matters worse for homeowners, President Donald Trump’s tariffs on imported steel and aluminum have been at 50 percent since June 2025. Imported softwood lumber carries a 10 percent tariff, and Canadian lumber carries roughly 35 percent in additional duties on top of that, even though Canada supplies about three-quarters of the softwood lumber we import. UBS estimates the tariffs add $7,913 to the cost of a new home and the builders’ own survey put it as high as $10,900. The Supreme Court struck down a chunk of the president’s tariffs in February, but the steel, aluminum, and lumber tariffs rest on a different statutory framework that remains in place.
Then there is the concrete. Data center construction is the one red-hot market the American Cement Association sees right now, and one major producer reported that a high single-digit share of its ready-mix volume this year was tied to artificial intelligence. Ready-mix concrete and concrete block prices are sitting near their highest levels since the pandemic. Any builder ordering concrete for any project is now bidding against Amazon, Meta, and Microsoft. The market will, over time, sort this portion of costs out without government interference. But it is all the more reason for the government to stop piling on the costs it does control.
Interest rates make every one of those costs worse. Freddie Mac’s average 30-year mortgage rate was 7.18 percent last week, nearly a full point higher than a year ago. At that rate, the $40,288 in code changes over the past decade adds about $270 to a monthly payment and nearly $100,000 over the life of the loan.
Nobody in Washington can order mortgage rates down, nor should any of them tell the tech companies to stop pouring foundations. Congress and the president can end the tariffs on building materials today. States and cities can adopt new codes with the costliest mandates stripped out, require a cost analysis that considers the impact on the buyer, and sunset requirements that haven’t proven their worth. They could even revert back to older regulations. Republicans say they want Americans to own homes. The parts of the problem they can actually fix are the parts they keep letting bureaucrats make worse. It does not have to be that way.
Views expressed in this article are the opinions of the author and do not necessarily reflect the views of The Epoch Times.