Commentary
In 1978, the year I was born, my great-grandfather bought me a U.S. government bond.
My great-grandfather had only one leg. He lost the other in World War I. I wish I could tell you exactly what kind of bond he bought me, but nearly half a century later, I can’t.
What I can still picture is the bond itself. It was blue, big, and official-looking, almost like an oversized piece of currency. There was a large dollar amount printed across it, and I understood that someday it would be worth considerably more.
What I remember much more clearly is being a teenager and talking my mother into letting me cash it before it had finished doing whatever mysterious thing bonds were supposed to do. I got a couple thousand dollars and did what teenagers do with money they didn’t earn and don’t understand.
I bought a leather jacket. I bought Madonna’s new book, which was basically softcore porn. I went to concerts, went out with my friends, and spent it on things that seemed terribly important at the time and that I can barely remember now.
What I didn’t do was ask a basic question: What exactly had my great-grandfather bought?
I knew he had exchanged money for this strange blue piece of paper. I knew that somehow, by leaving it alone, it became worth more. I knew the U.S. government had something to do with it. That was about the extent of my understanding of the bond market.
I am 48 years old now. I own businesses, employ people, have borrowed money, paid taxes, bought and sold property, invested, farmed, closed restaurants, and spent much of my adult life paying attention to government and economics. Yet the gaps in my understanding of our monetary system still sometimes feel like caverns the size of the Grand Canyon.
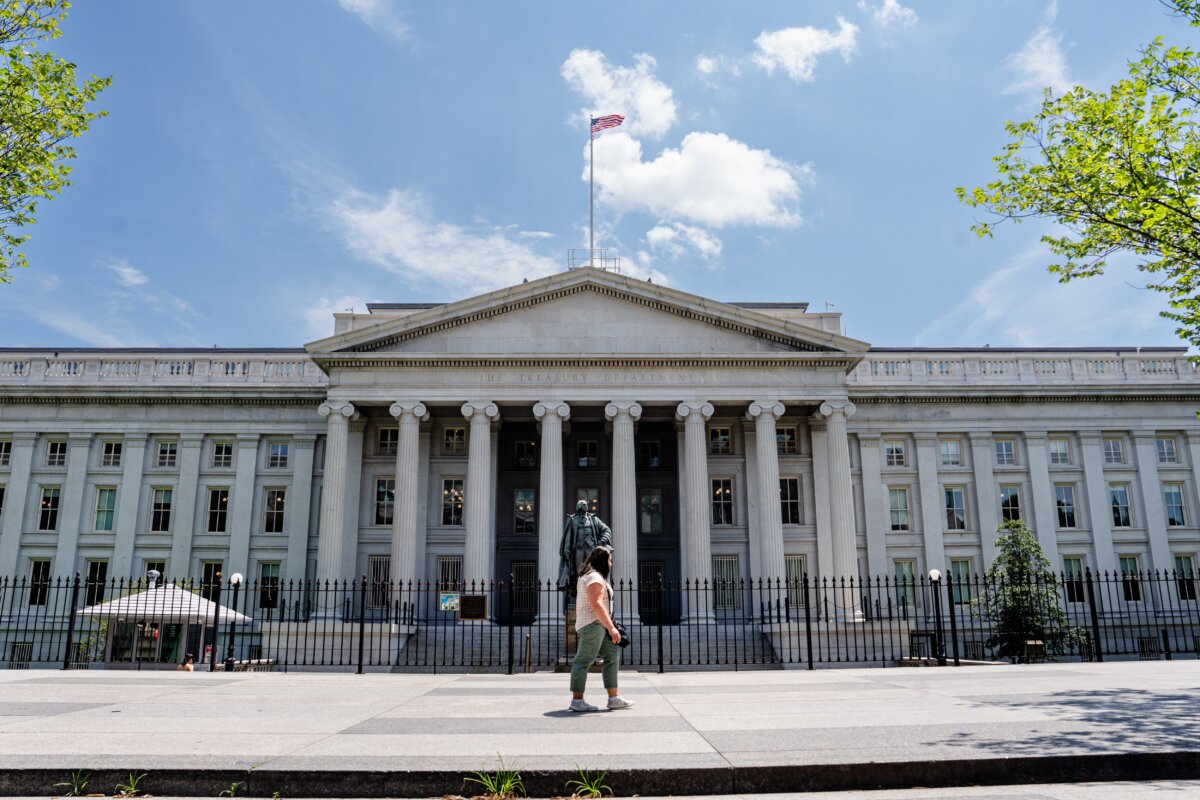
This week provided a wonderful example. The U.S. Treasury increased the maximum size of certain long-term Treasury buybacks from $2 billion to $6 billion. Financial news starts throwing around words such as “liquidity,” “repo,” “Treasury buyback,” “reserves,” and “quantitative easing,” and I suspect that most Americans have no idea what any of it means.
So let’s make it painfully simple.
When the United States spends more money than it collects, it borrows the difference by selling debt. A Treasury security is essentially an IOU from the U.S. government. Investors lend money to the government, and the government promises to repay it according to the terms of that security.
Today, the federal debt is more than $38 trillion. A number that large almost stops meaning anything, but the debt isn’t imaginary. Somebody owns those IOUs: households, banks, pension funds, insurance companies, investment funds, foreign investors, and foreign governments. And the United States continually needs more buyers.
When investors become less enthusiastic about lending the United States money for 10, 20, or 30 years, they don’t necessarily walk away. They can demand a better deal. In the bond market, that means higher yields.
Imagine lending money to two friends. One has little debt, plenty of income, and always pays you back. The other already owes everybody in town and asks you for another loan. You might still lend to him, but you’re probably going to want more interest.
Now, consider this week’s buyback. Treasury is offering to purchase some older government securities from investors. These aren’t delinquent mortgages or consumer loans people can’t afford. They are America’s own previously issued IOUs. Treasury says purchasing older, less actively traded securities helps the market function smoothly and improves liquidity.
Liquidity simply means: Can I turn this thing into spendable money easily and at a reasonable price? Cash is extremely liquid. A tractor isn’t. My ranch might contain valuable land, cattle, and equipment, but if payroll is tomorrow and the checking account is empty, owning a tractor doesn’t solve tonight’s liquidity problem.
Then there is the repo market. Imagine I need cash tonight, so I give you a Treasury security as collateral. You give me cash, and I agree to buy the security back shortly afterward for slightly more. Essentially, it is an extremely short-term collateralized loan.
Quantitative easing, or QE, is different again. When the Federal Reserve conducts QE, it purchases financial assets and can pay for them by creating new reserve balances electronically.
In plain English, new central-bank money is created.
No printing press needs to start running. The money is created electronically. Calling it “printing money” isn’t a literal description of the physical process, but money creation isn’t a conspiracy theory. It is part of our monetary system.
And the Fed isn’t the only place where money creation occurs.
I was talking with my neighbor Chuck about a tractor payment or financing some piece of farm equipment. I said, “Well, it’s not really like they had a pile of money sitting there and lent us some of it. The money was created when we signed for the loan.”
Chuck looked at me like I had lost my mind.
“That can’t be right, Mollie. Obviously, they have a pile of money, and they’re lending you money from the pile.”
He still brings up “that crazy thing you told me about banks creating money.”
But Chuck’s understanding was exactly what mine had been for most of my life. We imagine depositing $1,000 into a bank, the bank adding it to a giant pile, and then lending $800 from that pile to somebody else.
Modern bank lending doesn’t quite work that way. When a commercial bank approves a $100,000 loan, it generally records the loan as an asset and simultaneously creates a $100,000 deposit in the borrower’s account. New bank deposit money has been created.
Banks can’t do this infinitely. They face capital requirements, liquidity constraints, funding costs, regulation, and credit risk. But the underlying mechanism is still astonishing when you first understand it.
If I lend Chuck my tractor, I have to possess a tractor. If I lend him $100, I need $100. If I lend him 10 bales of hay, 10 bales leave my barn. Bank lending doesn’t work quite that way.
Eventually, the borrower must repay the loan. To obtain those dollars, I have to participate in the real economy. I raise something, cook something, sell something, or provide a service. When the principal is repaid, the corresponding bank-created deposit money is effectively extinguished as the loan balance falls. But I also owe interest, which becomes income to the bank.
There is something almost philosophical about this exchange. Credit can be created with accounting entries, but borrowers generally repay it through participation in the real economy.
Money creation can also be thought of as a form of dilution. If claims on goods and services grow much faster than the amount of actual goods and services available, more money is competing for the same real things. That doesn’t mean increasing the money supply by 10 percent automatically raises every price by 10 percent, but creating money isn’t meaningless simply because nobody physically printed it.
A dollar represents a claim on real things: someone’s labor, milk, diesel, lumber, land. We can create additional dollars with accounting entries. We cannot create additional cows, houses, wheat, oil, or hours in a human life quite so easily.
Which brings us back to Treasury. This week’s $6 billion buyback is not the Fed printing $6 billion. A Treasury buyback, a repo operation, and quantitative easing may all involve huge sums moving through the financial system, but they are different things.
What interests me isn’t really the $6 billion—it is that the maximum for these particular long-duration liquidity-support purchases rose from $2 billion to $6 billion even as investors have been demanding higher yields on long-term government debt.
Higher Treasury yields influence mortgages and business borrowing, and they increase the cost of servicing our enormous federal debt. Eventually, the government can find itself borrowing additional money partly to pay interest on money it already borrowed.
And this is where I start asking a question that doesn’t feel Republican or Democratic anymore: What exactly is a fiscal conservative in 2026?
I’m not sure I know. The national debt has grown under Republican and Democratic presidents and Congresses. We argue ferociously over which party is financially responsible while the debt chart keeps climbing.
Perhaps Americans would demand different things from the government if they understood how the machinery works. Instead, we hear $10 trillion, $20 trillion, $30 trillion, and now more than $38 trillion until the numbers become abstractions. Treasury conducted a buyback. The repo market needed liquidity. The Fed expanded its balance sheet. The words wash over us.
Sometimes, I wonder whether some of that confusion is useful to the people running the system.
I can’t prove that our monetary system was intentionally designed to be incomprehensible. Much of its complexity accumulated over generations of laws, crises, institutions, and financial inventions. But complexity has a convenient consequence: It makes public scrutiny difficult. Perhaps nobody had to design the confusion. Perhaps complexity simply protects itself.
I don’t think most Americans are stupid. I think we have constructed a monetary system whose language is almost incomprehensible to the people whose lives depend upon it.
At 48, I also see that blue bond differently. My great-grandfather had already given a leg to his country in World War I. Decades later, he was still willing to lend his money to that same country and leave its promise to repay to his great-granddaughter.
There is something beautiful about that to me now, and something painful about remembering how I spent it. I certainly didn’t honor the history behind that money because I didn’t understand it.
That blue piece of paper represented debt, trust, and a promise. My great-grandfather trusted that the U.S. government’s promise would still mean something years after he was gone.
Maybe before we argue about the next trillion dollars of spending, every American should understand what a Treasury bond is, where bank money comes from, and what it means when our financial system needs more “liquidity.”
My great-grandfather believed that America’s promises were worth buying.
We should probably understand what we’re promising before we issue trillions more.
Views expressed in this article are the opinions of the author and do not necessarily reflect the views of The Epoch Times.







