Commentary
Chinese leader Xi Jinping has spent a fortune pursuing great ambitions for China—military, monetary, diplomatic, and technological. He has had his successes, but the effort has also inundated the country with an ocean of debt, often without any realistic promise of the kinds of returns that can service it. This relative debt load now exceeds that of most any other country, including even the United States. It bodes ill for China’s economic and financial future.
In one respect, China’s finances do look relatively strong. Direct debt obligations of the central government, plus certain aspects of local government debt, amounted in 2025 to a bit less than 100 trillion yuan (about $14.9 trillion), some 70 percent of China’s gross domestic product (GDP). That compares favorably with most any other developed country, including the United States. Washington’s debt obligations, for instance, stand today at close to 127 percent of U.S. GDP. Adding in the $3.8 trillion in direct state and local debt (about 11.7 percent of U.S. GDP) brings the U.S. total for all levels of government to about 139 percent of the economy, a much higher figure than in China.
Private debt burdens also look comparatively good for China. Individual debt in China, including mortgage debt, amounts to some 83 trillion yuan (about $12.4 trillion). Private businesses carry about 68 trillion yuan (about $15 trillion) in debt, bringing the total of private debt outstanding to some 151 trillion yuan (about $23 trillion), some 104 percent of China’s GDP. In the United States, business and individual debt combined come to about 138 percent of GDP, quite a bit higher than in China.
But these lines of inquiry are only a part of China’s debt story. Burdens created by state-owned enterprises change the plot line radically. Because Chinese policy has imposed most of the cost and borrowing for infrastructure projects, social welfare, and most government services on provincial and local governments and because the property crisis has cost these governments revenues from taxes and fees on land transfers, provincial authorities have had to borrow heavily to fulfill their obligations to their residents. Direct borrowing, counted above, is only a small part of this story. Many provincial and local governments have borrowed off balance sheets through special vehicles set up as state-owned enterprises. This kind of borrowing, plus the borrowing of more conventional state-owned companies, amounts to a whopping 201 trillion yuan (about $30 trillion), about 140 percent of China’s GDP.
These staggering obligations dominate the totals. For the United States, without much of a state-owned enterprise sector, the overall figure for outstanding debt settles at just about 270 percent of GDP. In China, it amounts to about 314 percent of GDP, a gap of almost 50 percentage points.
This difference is still more significant when considering that the United States is a much more fully developed economy than China’s and so has much greater asset backing. That asset base should enable it to manage a larger relative debt load. The difference in the household sector is indicative. A McKinsey report puts American household net worth at 2 1/2 times that of China. The differences in the relative asset bases of the two countries’ business sectors are probably greater than in the household sector, although definite statistical comparisons are hard to come by.
Perhaps still more significant is the relative insecurity of China’s debt. Things, of course, can change, but presently, finances in the United States look pretty stable. Banks report a net loan charge-off rate of only 0.6 percent. In contrast, China is still suffering from a property crisis that threatens to create still more bad debt, especially since the crisis is depressing property values and hence household net worth. Already in China, banks report that non-payments have risen to 1.5 percent of outstanding loans. Nor does any of this consider the precarious nature of China’s financial exposure in poorer countries through the lending state-owned banks and companies have made in the Belt and Road Initiative.
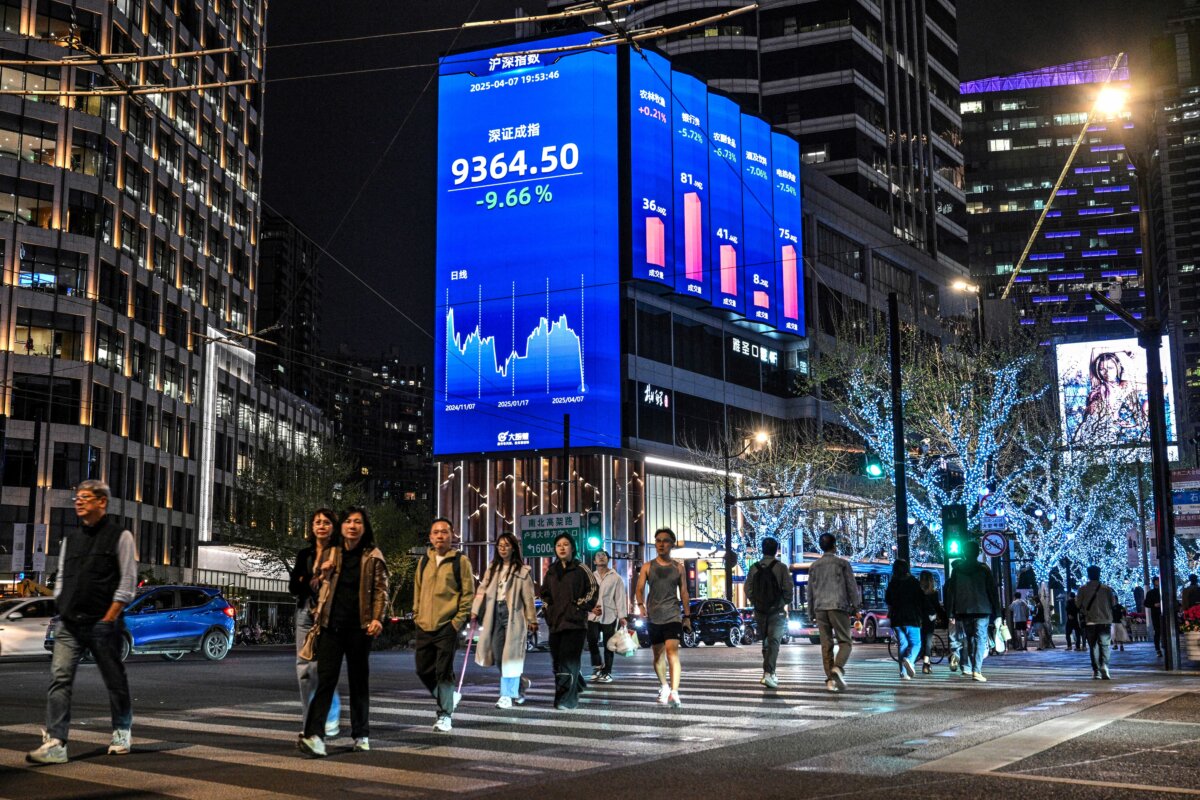
China’s debt overhang cannot help but color the economy’s prospects—and not in the brightest of hues. The property crisis with which China has struggled since 2021 makes this fact painfully clear. Financial strains limit the system’s ability to support promising future endeavors, and financial failures speak to economic choices that lead to waste of economic resources—natural, labor, and intellectual as well as capital—not growth. China’s sad economic slowdown since 2021 gives real world testimony to this fact.
Things can, of course, change. Economies have been known to power through the kinds of constraints implicit in China’s debt burdens. Still, this relative debt matter puts Chinese growth probabilities more on the low than on the high side. As Jacob Gunter, head of the economic and industry program of the Berlin-based Mercator Institute for China Studies, said of this situation: “We are seeing a system running into some of its limits.”
Views expressed in this article are the opinions of the author and do not necessarily reflect the views of The Epoch Times.